The Science Behind

Products you already know, traced to the research

Each piece opens on a real object or checkout you can still buy or open today, then names the cited mechanism behind how it works. Filter by category, or search for a product by name.


By signal

Why does raw selvedge denim feel like better quality than jeans that actually fit?

Raw selvedge jeans use narrower cloth, leave the hem unfinished, and skip stretch, yet sell for several times a regular pair. The four mechanisms below show how those traits get interpreted once someone is shopping.

Craft & Materials What Looks Handmade
Meaningless Differentiation

Cuff a raw pair and the outseam shows a selvedge: a tightly bound, self-finished edge. That edge exists because the cloth came off a narrow, slow shuttle loom rather than a wide modern one. Fit, wear life, and dye retention stay the same either way; the selvedge alone does not improve any of those.

Shoppers rarely need the loom history. The cuffed edge still reads as proof of a slower, more careful process. Meaningless Differentiation covers that swap: a specific, hard-to-fake detail standing in for a quality check nobody actually ran, the same pattern as an invented fabric grade.

IKEA Effect

The selvedge does its work on the shop floor. Once the pair leaves the store, a second mechanism takes over. Raw denim ships unwashed and untreated on purpose. Months of sitting, kneeling, and carrying a phone crease and fade the cloth along the owner's own habits. IKEA Effect here runs after checkout: break-in labour is real, and it is what makes two worn pairs of the identical model look nothing alike.

Scarcity

Those two effects would still apply if raw denim were everywhere. Capacity is why it stayed uncommon. Old shuttle looms weave a narrower bolt, and they do it much more slowly than today's wide projectile looms. Cone Mills' White Oak plant, once the last large American shuttle-weaving mill, closed for good in 2017. Japan's Kojima district kept its old Toyoda shuttle looms running because the slower weave produced better fades. Scarcity here tracks real, shrinking production capacity as those looms retire.

Halo Effect

Hard-to-get fabric is one story. What people infer from owning it is another. “Woven on the same looms for decades” is a true production claim. Buyers often treat it as a stand-in for stitch strength, dye behaviour, and fit quality, claims the loom fact never tested. Halo Effect is the name for that leap: one real, verifiable trait standing in for others nobody checked. On a single pair the four mechanisms pile up. The edge substitutes for a quality check. Break-in labour becomes part of the product story. A real bottleneck reads as prestige. One true loom fact carries untested claims with it.

Real vs. perceived
Genuinely real
  • A shuttle loom's narrower bolt and slower pace cut real output versus a modern wide loom
  • A self-finished selvedge edge resists fraying without stitching, a genuine structural difference
  • Unwashed indigo fades unevenly and maps the wearer's own habits over months
Psychological framing
  • Meaningless Differentiation: the cuffed edge reads as quality proof even when the buyer cannot say why it is there
  • IKEA Effect: break-in labour is sold as part of the product itself
  • Halo Effect: loom provenance gets borrowed as evidence of durability nobody measured
Sources

Mechanism citations sit on each linked Principles entry, with the academic study attached there. Denim production history here comes from industry references rather than academic papers, including Redcast Heritage's history of Japanese denim, Heddels' field tour of Kojima's shuttle and projectile looms, and Okayama Denim's account of the Toyoda G3 shuttle loom.

Real examples

Operating brands listed only to show the price range this mechanism spans. None of them is an endorsement. Prices shift; use each brand's own site for a current figure.


Why does the same coffee taste sweeter from one side of this pink cup than the other?

A 200ml porcelain filter cup: thin lip on one side, thick lip on the other, soft pink glaze. The brew stays the same; the vessel's cues do the work.

Food & Drink What Feels Premium
Crossmodal Correspondence

Touch and sight both get a turn before taste does, so the same sip is nudged twice. Each cue rests on its own experiment; neither study is being stretched to cover the other.

The rim

Wall thickness varies around the rim on purpose. From the thick side, a thicker layer of tea lands on the tongue. From the thin side, a thinner layer lands instead.

THE SAME TEA TASTES DIFFERENT POURED FROM A DIFFERENT-LIPPED GLASS POURED FROM A THICK-LIPPED GLASS RATED SWEETER Identical tea, same temperature POURED FROM A THIN-LIPPED GLASS RATED MORE BITTER The identical tea, poured moments apart Nothing in the tea changed. Only the glass touching the lips did.

Ichimura, Motoki, Matsushita & Ariga (2023) varied only the glass lip's physical thickness and gave the same tasters identical tea from each glass, so touch was the sole manipulated variable.

The glaze

Colour starts earlier still, before the first sip. Pink belongs to the colour family that this mug study found shifting taste on its own.

THE SAME LATTE TASTES DIFFERENT POURED INTO A DIFFERENT COLOURED MUG POURED INTO A WHITE MUG RATED LESS SWEET, MORE INTENSE Same coffee, same temperature POURED INTO A BLUE MUG RATED SWEETER, LESS INTENSE The identical latte, poured seconds apart Nothing in the cup changed. Only the colour holding it did.

Van Doorn, Wuillemin & Spence (2014) poured the same latte from the same jug into a white mug, a blue mug, and a clear glass, holding every variable except colour constant. The cup's maker leans on that finding in its listing, claiming the glaze alone lifts perceived sweetness by up to 40%. That figure is the brand's own claim, not an independently verified measurement.

The coffee itself never changes. Both cues still count as Crossmodal Correspondence: one sense filling in a judgment the tongue alone never made.

Real vs. perceived
Genuinely real
  • One side of the rim is measurably thicker than the other: a real geometric difference
  • A small dimple moulded into the base changes how liquid and sediment settle and swirl
  • Whichever side is used, the coffee inside stays the same liquid, temperature, and chemistry
  • Designed with World Brewers Cup Champion Jerome Rosler for professional cupping, beyond decoration alone
Psychological framing
Sources

The Crossmodal Correspondence citation, with its study card, lives on the Principles page entry: Van Doorn, G. H., Wuillemin, D., & Spence, C. (2014). “Does the Colour of the Mug Influence the Taste of the Coffee?” Flavour, 3, Article 10. A second study backs the rim-thickness claim: Ichimura, F., Motoki, K., Matsushita, K., & Ariga, A. (2023). “The Tactile Thickness of the Lip and Weight of a Glass Can Modulate Sensory Perception of Tea Beverage.” Food and Humanity, 1, 180–187. Both papers sat behind this site's network restrictions, so the findings above, and both illustrations, are paraphrased from their abstracts and secondary academic summaries, not quoted verbatim or reproduced from the original figures.

Real examples
  • Ni Wares, Kiki 200ml dual-lip porcelain filter cup, designed with World Brewers Cup Champion Jerome Rosler, around $40 ni-wares.com
  • Ni Wares, Bouba The same maker's rounder dual-lip cup, named for the classic “bouba/kiki” sound-shape pairing ni-wares.com

Operating products listed to show the mechanism in the wild. Neither is an endorsement. Prices shift; use each brand's own site for a current figure.


Why does Afterpay's four-dot progress bar make the same $100 feel smaller?

On Afterpay's checkout button, choosing “Pay in 4” turns a $100 order into four payments of $25. One charge lands today; the other three follow every two weeks, and the schedule stays interest-free. The button itself shows four dots in place of a single total.

That one control stacks four separate mechanisms. Each targets a different judgment of the same $100: how large it feels, when it hurts, what the credit costs, and how much the tap itself feels like spending.

Tech & Product Design What Feels Affordable
Chunking

Look at the dollar figure first. Afterpay's schedule is literal bookkeeping: a real $100 order becomes four real, separate $25 charges, one today and the rest every two weeks. Chunking breaks one large ask into several smaller ones over time, the same logic as any instalment plan. Each $25 charge is a smaller ask than $100 at once, which is why it clears a mental bar the full amount would miss.

Present Bias

Splitting the total still leaves the calendar alone. Afterpay also splits when the money leaves. The order ships today and the first payment is due today. The remaining three charges, 75% of the real cost, land two, four, and six weeks later. Those later dates feel abstract next to the vivid fact of having the goods now. Present Bias weights a reward available today far more heavily than the same cost delayed by a few weeks.

Zero Price Effect

The credit price gets rewritten the same way the calendar does. Afterpay's other headline line is “Always interest-free,” and for Pay in 4 that fee is literally $0 for spreading the order out. A borrowing cost that hits zero tends to jump categories in a shopper's head, the disproportionate pull Zero Price Effect documents for a product's price. Here the zero attaches to the credit, while the order total stays $100.

Payment Transparency

A $0 fee still leaves real money to pay later. The final lever is how the authorisation feels. One tap that green-lights four future charges is more abstracted than handing over $100 in cash, or typing a card number for the full amount once. The site calls that Payment Transparency: the less a payment feels like money leaving, the less it hurts, and the easier yes becomes. Afterpay's button already works that lever alongside size, timing, and credit cost.

Real vs. perceived
Genuinely real
  • On-time, the total charged is still the same $100, taken as four real payments two weeks apart
  • Afterpay's approval uses a soft check rather than a full credit application, unlike a traditional instalment loan
  • A missed payment triggers a real late fee, capped under Afterpay's published terms
Psychological framing
  • Chunking: four $25 charges clear a mental bar that one $100 charge would miss
  • Present Bias: goods and the first payment arrive now; the other 75% of the cost sits in an abstract future
  • Zero Price Effect: a literal $0 fee on the credit reads as a different offer than a small percentage would
  • Payment Transparency: one authorisation for four future charges feels less like spending than handing over $100 at once
Sources

Each of the four mechanisms above is cited on its own Principles entry. That covers Chunking, Present Bias (Read & van Leeuwen, 1998), Zero Price Effect, and Payment Transparency. Afterpay's schedule, approval process, and fee structure come from Afterpay's public “How It Works” page; terms change, so check that page rather than treating this summary as current.

Real examples
  • Afterpay, Pay in 4 The product decoded above: 4 instalments, 2 weeks apart, soft credit check afterpay.com
  • Klarna Its own “Pay in 4” plan runs the identical schedule, plus longer financed plans on larger purchases klarna.com
  • Affirm Some plans interest-free like Afterpay's, others carry disclosed interest shown before checkout affirm.com

Operating providers listed to show the same pattern elsewhere. None is an endorsement. Terms and fees shift; use each provider's own site for what applies today.


How do you trust a shirt you've never tried on, the first time and every time after?

Proper Cloth, founded in New York in 2008, sells made-to-measure shirts online. Son of a Tailor, founded in Copenhagen in 2014, sells made-to-order t-shirts the same way. The shared pitch is a garment cut for one body, bought from a company that has never seen that body in person.

A first order hits five practical questions in a fixed order: sizing from sparse data, what happens when that size is wrong, whether production labour stays hidden, how much the buyer designs before paying, and why a stranger would trust the process before any cloth is cut.

On sizing, design, and first-buyer trust the two brands land in almost the same place. Remakes versus named labour is where they diverge, and that split is the useful part of the comparison. A later section covers how those five questions change once the customer already owns a shirt.

Tech & Product Design What Feels Premium
Take-the-Best Heuristic

Online clothing still starts with a sizing problem: predicting fit without a fitting room. Proper Cloth's Smart Sizes quiz covers height, weight, body shape, and preferred shirt drape, then scores those answers against tens of thousands of earlier customers' measured profiles. From that, it forecasts 16 fit points (collar, chest, sleeve, and the rest) with no tape measure in the buyer's hands. Son of a Tailor asks even less. Its Ideal Size model uses five multiple-choice items (height, weight, age, jeans size, shoe size) and the same kind of outcome-trained regression. Son of a Tailor reports above 95% accuracy across more than 100,000 orders. That figure is the company's own marketing claim, not an independent study, so treat it as unverified until someone else repeats it. The behavioural finding does not need either percentage to be exact. Take-the-Best Heuristic is the pattern: a short list of cues that actually predict the outcome can match a longer self-report. Sixteen database-backed fit points usually beat a first-time buyer's home measurement. Five numbers people already know tend to do the same job.

Loss Aversion

Any statistical fit still fails for some bodies, and here the brands take opposite routes. Proper Cloth diagnoses the miss and cuts a replacement size at no extra charge. The sizing screen states that up front as free 60-day returns and remakes, before Add to Bag. Shirts from about $125 are made for one body; there is no rack size to swap into if the first cut is wrong, so the purchase carries a concrete downside before production starts. Under Loss Aversion, that downside weighs more than the upside of a good fit. Promising a remade shirt (rather than only a refund) is what lowers the barrier enough for many browsers to order.

Operational Transparency

Proper Cloth repairs a bad guess after the shirt exists. Son of a Tailor spends its energy making factory work visible before anything goes wrong. Every order gets its own generated pattern and is sewn end to end by one named person who signs the hangtag. Status updates in the account and by email mark each production stage, instead of a single “shipped” note at the end. A mass-market tee usually moves through anonymous hands on a line the buyer never sees. The site labels that contrast Operational Transparency: showing labour that would otherwise stay hidden raises how much people value the finished piece. An open kitchen does the same job for a plate; here the signature and the progress emails do it for cloth.

IKEA Effect

Remakes and signed hangtags only matter after someone has already ordered. The design step usually decides whether that order happens. Proper Cloth's configurator walks through hundreds of fabrics, more than 30 collar options, plus cuffs, plackets, and monograms, and can save the mix as a Style Profile. Son of a Tailor is lighter: colour, neckline, sleeve, pocket, and initials come before the sizing questions. Neither tool is a one-tap preset bundle; each asks for real choices. IKEA Effect is the finding that labour put into making something raises how much the maker values it. A 2020 customisation-tool study reported the same pattern: more genuine design choice predicts higher valuation of the finished item. A shirt the buyer configured feels more theirs than an off-the-rack pick, even when fabric quality is held constant.

Social Proof

Sizing, remakes, labour visibility, and design labour still leave a first buyer cold if they will not try the process. They are paying for cloth that does not exist yet, cut from a model of a body the company has never met. Proper Cloth sits at 4.9 out of 5 on Trustpilot across several hundred reviews, with repeated notes that free remakes were actually honoured. Earlier in the flow, the fit picker labels Slim as “Most Popular,” steering a new customer toward the option other buyers already chose. Son of a Tailor sits around 4.6 to 4.7 across more than 2,700 reviews, and many of those reviews single out the sewer's signature as part of why the wait felt justified. Social Proof converts those public tracks into permission. Other strangers vouch for the two risks that matter here: that the size lands close enough, and that the company treats the process (and the person sewing it) seriously. Aggregate ratings do not prove the algorithm works for any one body. They only show that enough people already ran the experiment and stayed glad they did, which is how the opening trust problem gets solved in practice.

What changes on the second order

The five stops above describe a stranger ordering before any shirt of theirs exists. A return customer still meets the same mechanisms, but the weights shift.

Take-the-Best Heuristic and Operational Transparency barely move. The saved Smart Sizes or Ideal Size profile is the earlier prediction reused. Production is still tracked per order, and Son of a Tailor still attaches a named sewer's signature.

Loss Aversion now guards a different comparison. First orders worry whether an unseen body can be guessed at all. Repeat orders worry whether a new fabric or style will match a shirt that already worked. The free remake still covers a miss, but the reference point is now the customer's own previous fit rather than a blank slate.

IKEA Effect only fires when there is a new design choice to make. Reordering the identical shirt skips that labour, so it does not earn the extra attachment a fresh colour or collar would. Social Proof matters least of all on a return visit. The first order needed strangers' reviews; the second already has stronger evidence: a shirt that arrived and fitted. That garment becomes the benchmark the next order is judged against.

Spotted in the wild

One real Proper Cloth purchase path: fit choice, checkout, complimentary remake, then the saved size profile that followed.
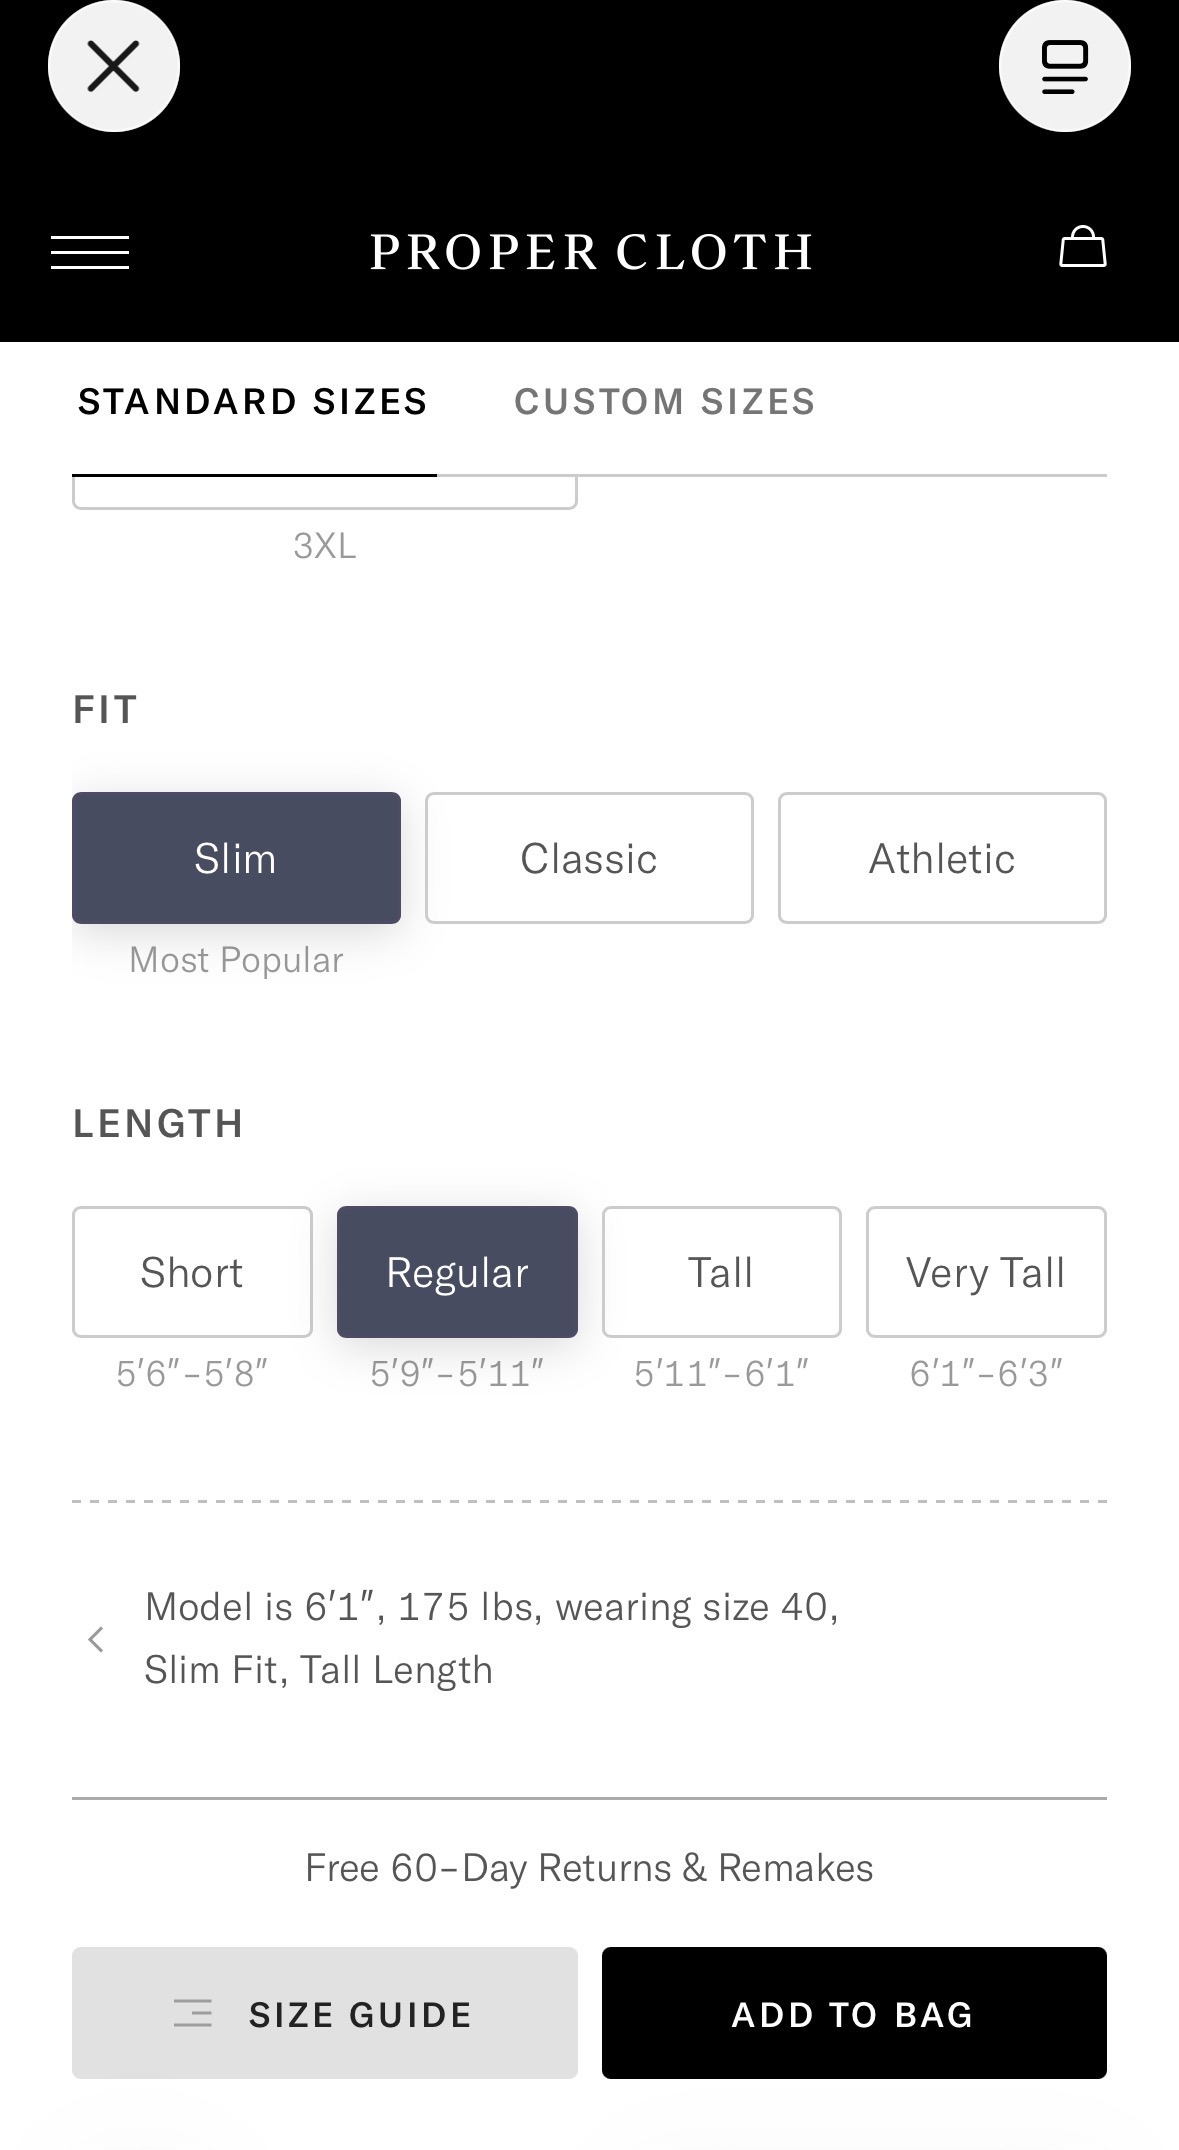
Proper Cloth's sizing screen showing the Slim fit tagged “Most Popular” and a “Free 60-Day Returns & Remakes” guarantee above the Add to Bag button

Sizing screen before commitment: Slim tagged “Most Popular,” with “Free 60-Day Returns & Remakes” sitting above Add to Bag. Social Proof and Loss Aversion are both on that one screen.
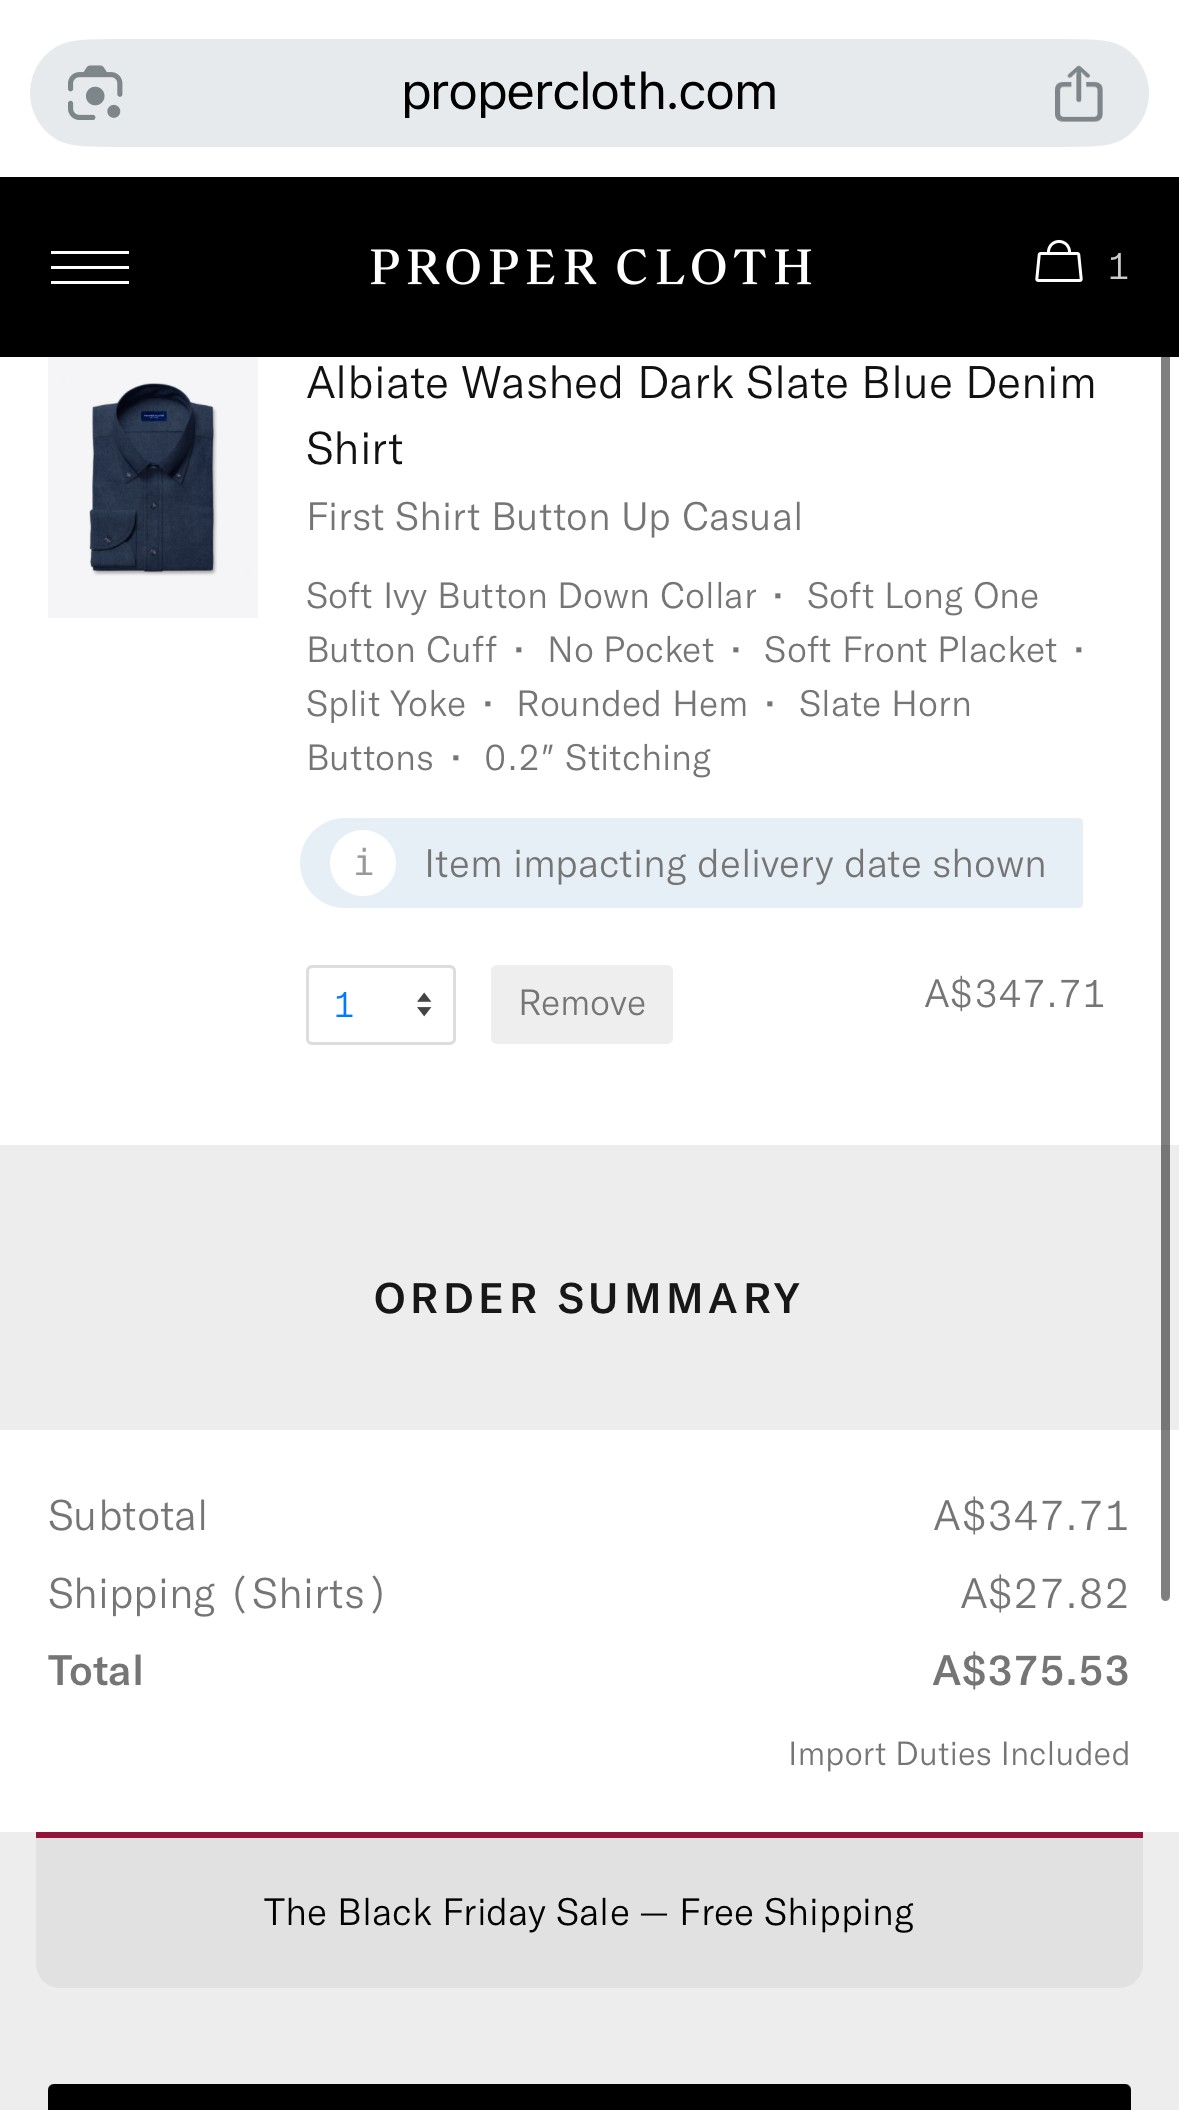
Proper Cloth checkout screen for an Albiate washed dark slate blue denim shirt, total A$375.53

Checkout for an Albiate washed dark slate blue denim shirt from the Smart Sizes path, A$375.53 including shipping.
An opened Proper Cloth shipping box with the folded shirt visible inside, in kraft-paper packaging

Arrival: the shirt inside Proper Cloth's recyclable kraft-paper packaging.
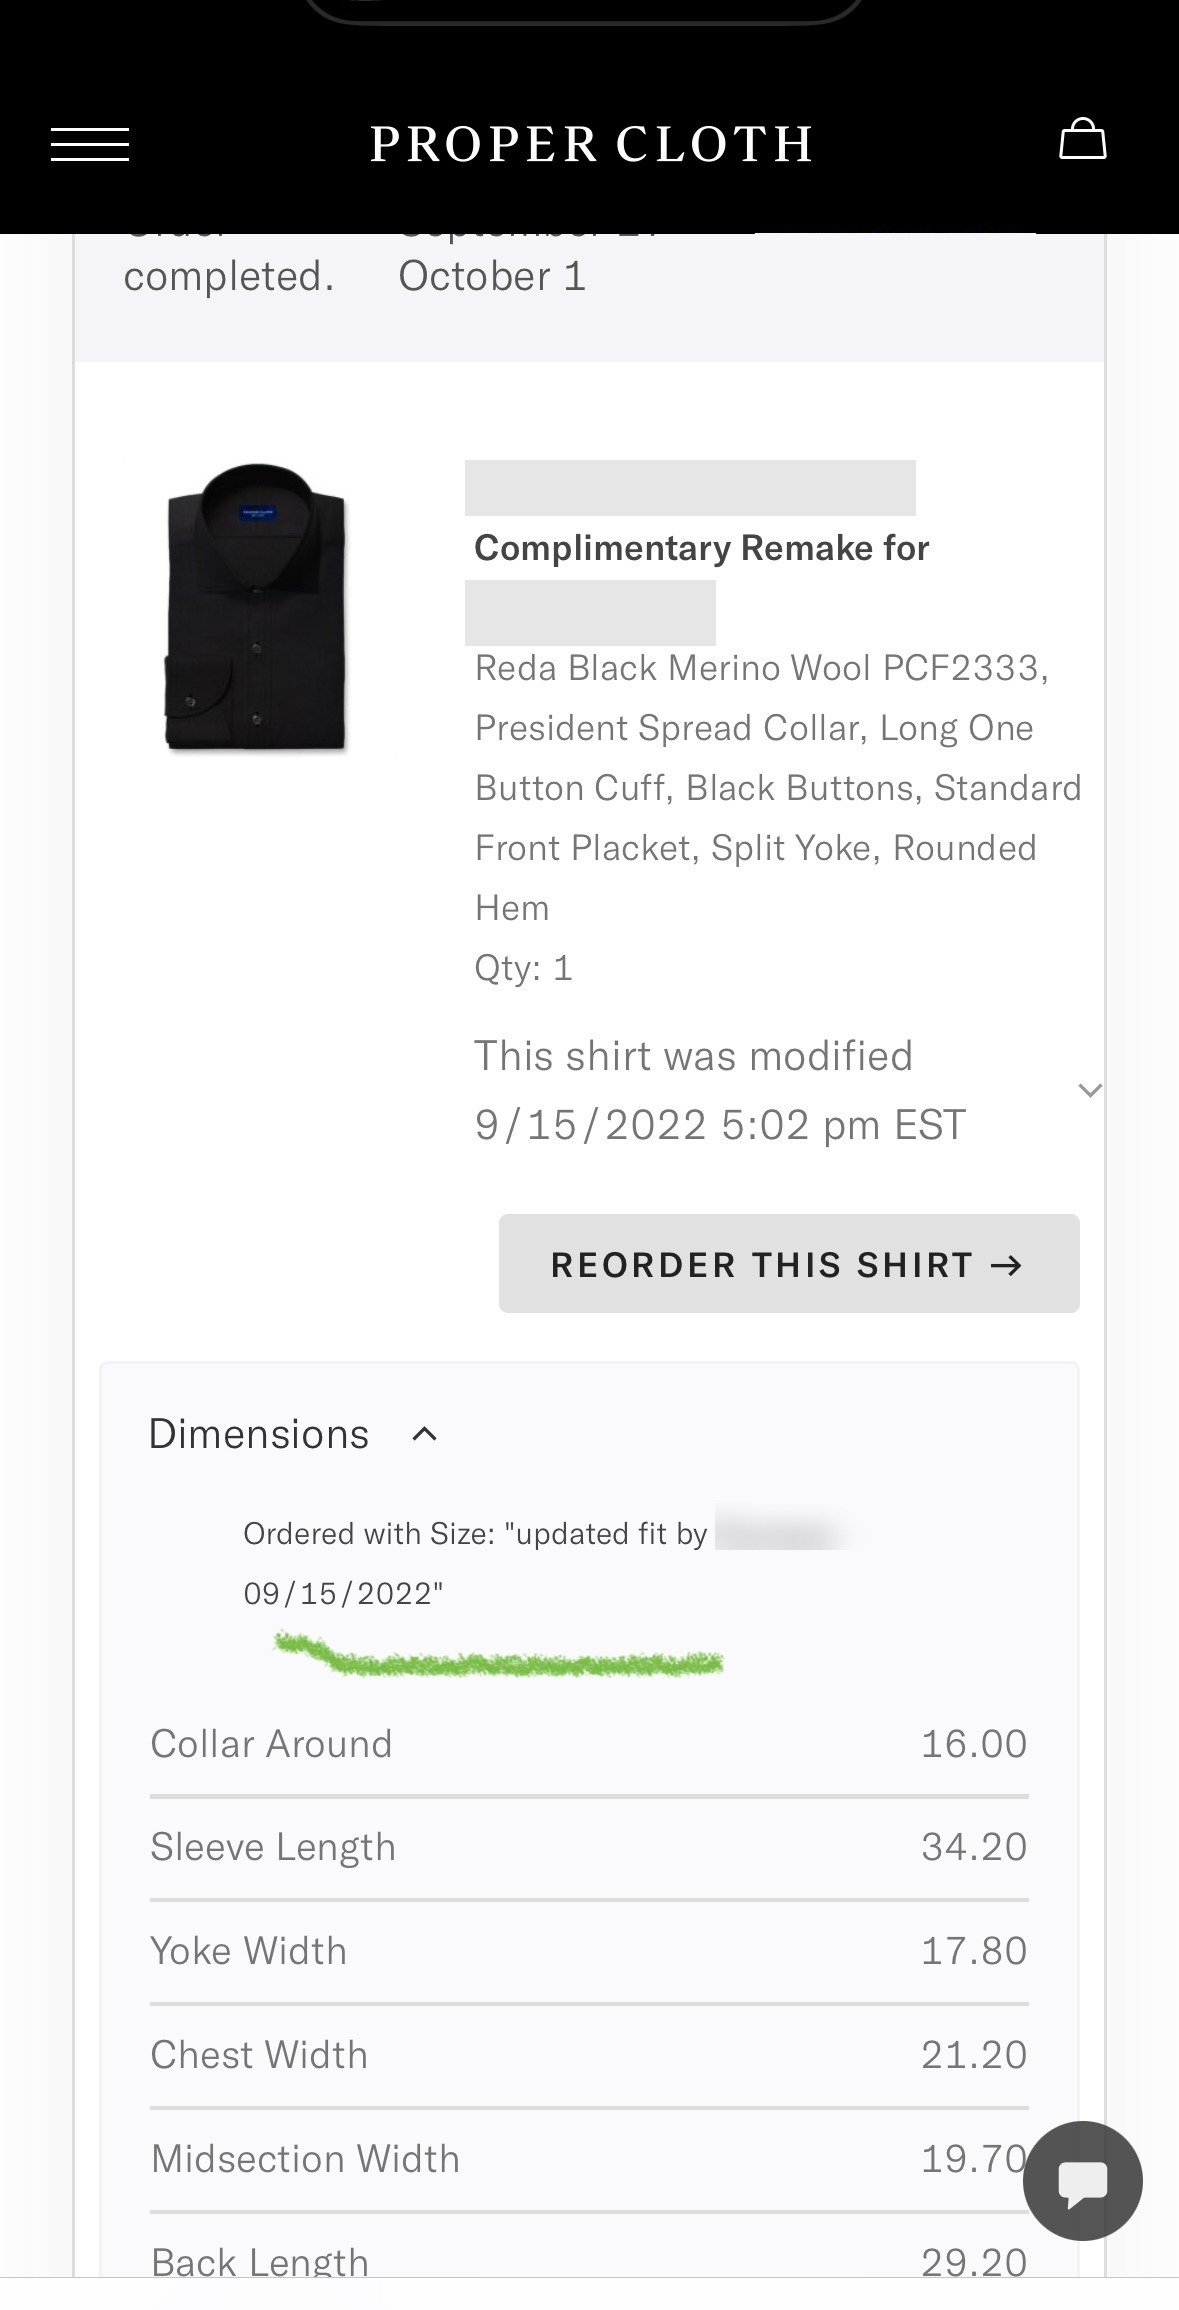
Proper Cloth order history showing a complimentary remake with updated fit dimensions, the staff member's name blurred

The remake policy in use: an order labelled “Complimentary Remake” after the first shirt's size was adjusted. The staff member's name is blurred for privacy.
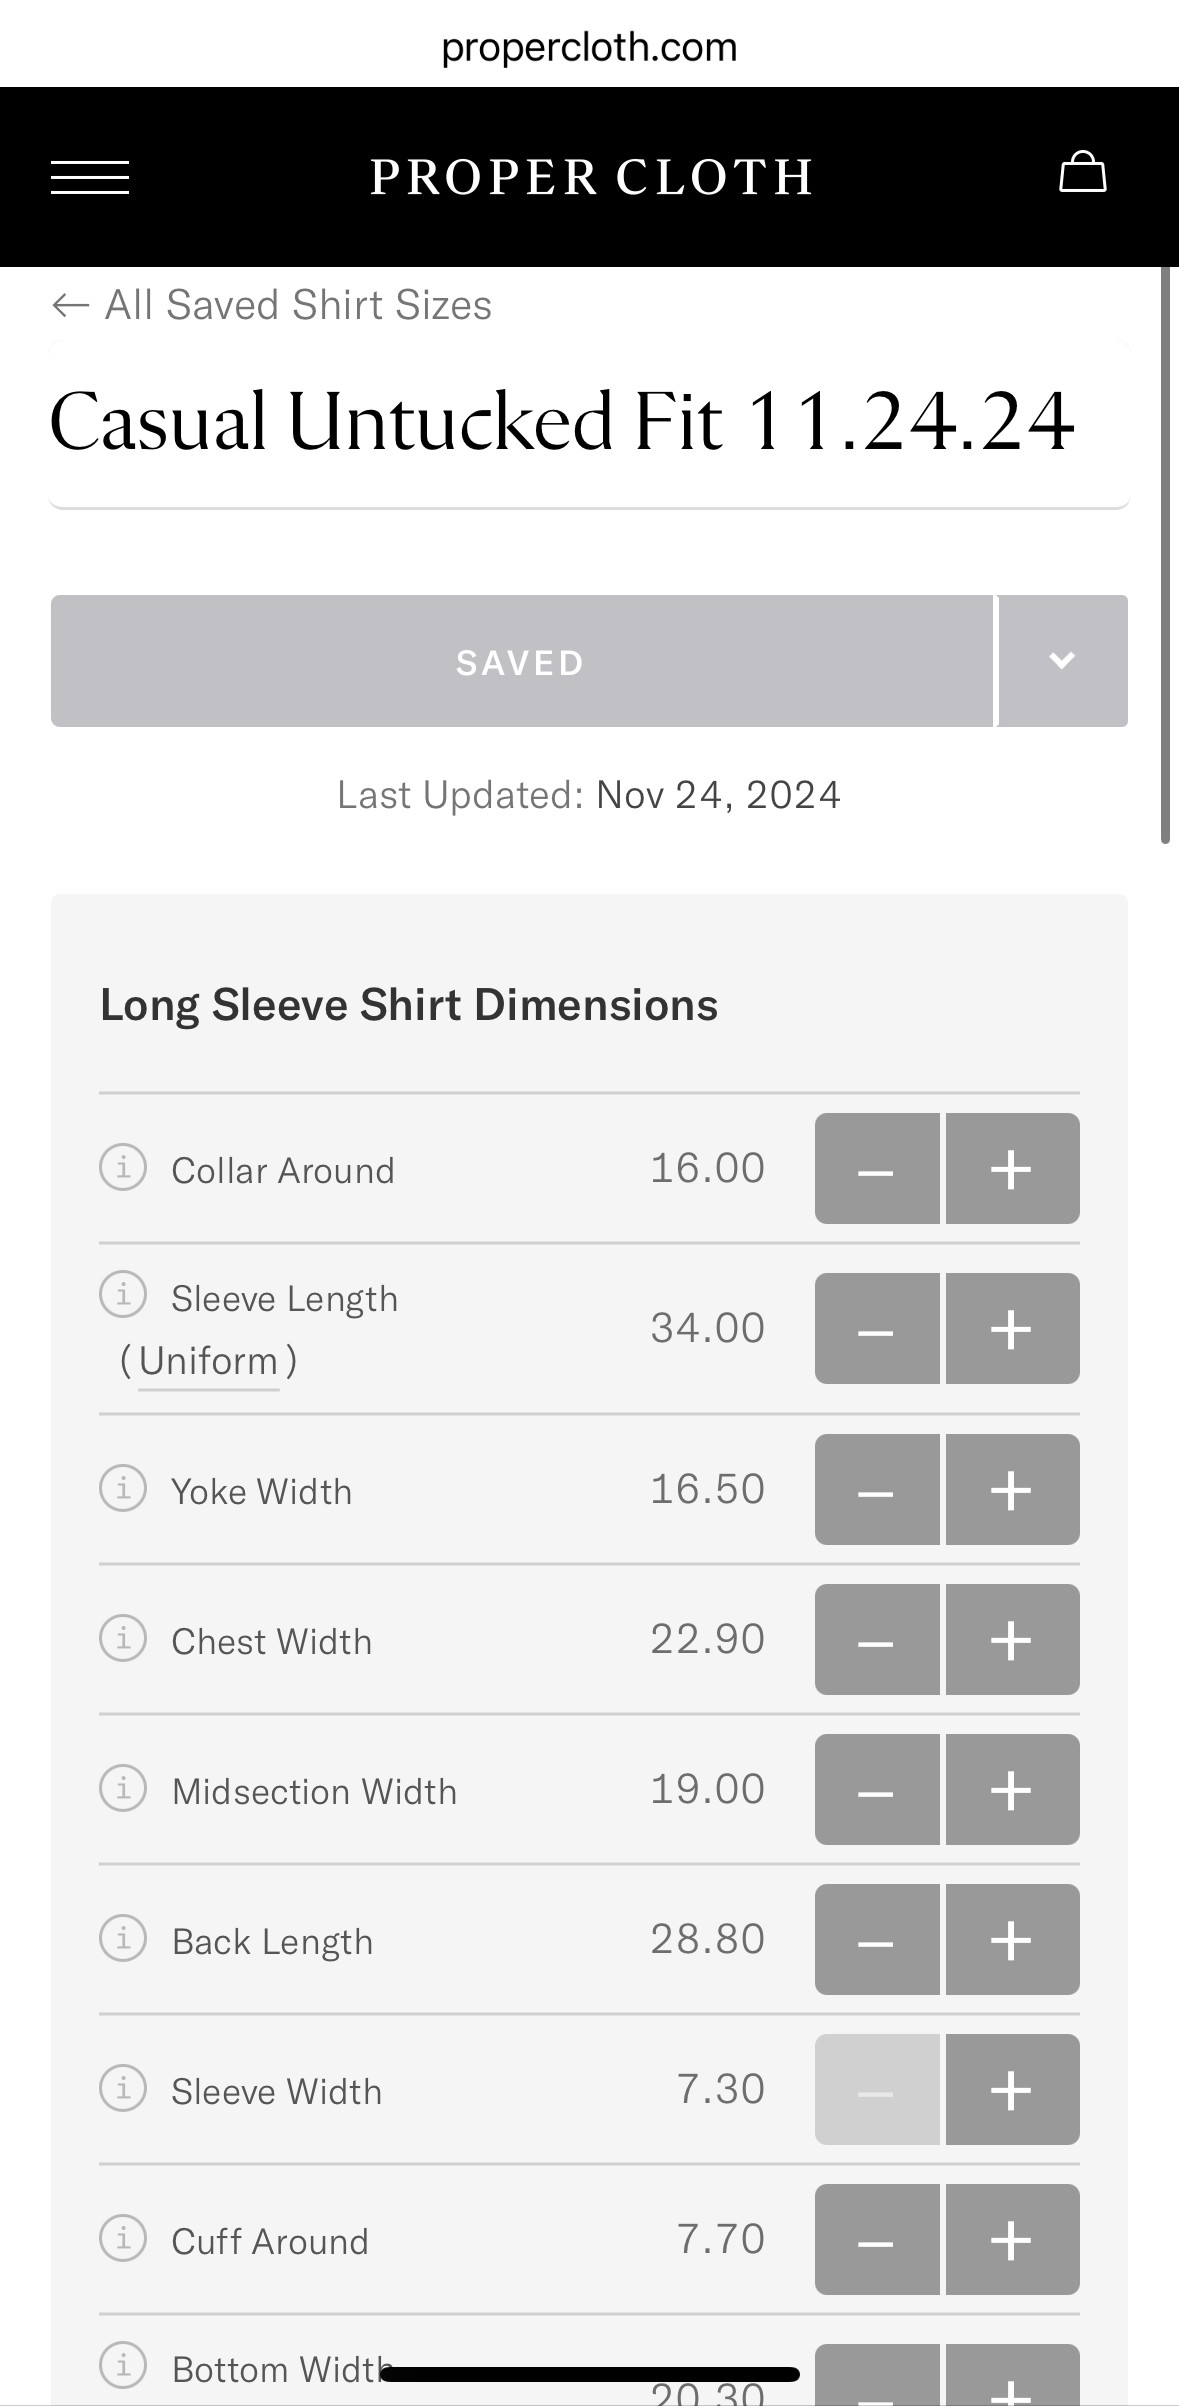
Proper Cloth saved shirt size profile showing real collar, sleeve, chest and other dimensions

Months later, the same customer's saved Smart Sizes profile: collar, sleeve, chest, and back length the algorithm is working from.

One customer's order and remake. It does not prove every fit lands first time, or that every order gets a remake. The “Most Popular” tag is Proper Cloth's own claim. Read the live policy on Proper Cloth's site rather than treating these terms as permanent.

Real vs. perceived
Genuinely real
  • Both quizzes forecast real fit points from past outcome data (16 for Proper Cloth; a full generated pattern for Son of a Tailor) without a customer tape measure
  • A mis-fitting Proper Cloth shirt is remade in a new size at no charge rather than only refunded
  • Each Son of a Tailor piece is cut from its own generated pattern, sewn by one named person who signs the hangtag, and tracked through production by account and email updates
  • Both design tools offer real fabric, colour, collar, and detail combinations chosen before or alongside fit, rather than a label on a few presets
  • Trustpilot ratings and review counts are third-party figures, not authored by either brand
Psychological framing
  • Take-the-Best Heuristic: a short quiz can feel like a close reading of one body when the model mostly reuses patterns from thousands of similar answers
  • Loss Aversion: a free remake reads as pure service goodwill while also removing the specific fear of paying for a shirt that cannot go back on a rack
  • Operational Transparency: a signed hangtag can feel like special attention to this order when the same signed step is standard on every garment
  • IKEA Effect: designing the shirt can feel like the main driver of quality when fit and cloth still come from the algorithm and the mill
  • Social Proof: a high star average can read as proof this page's mechanisms work when it averages shipping, service, and many other factors into one score
Sources

Take-the-Best Heuristic, Loss Aversion, Operational Transparency, IKEA Effect, and Social Proof each carry their academic citations on the linked Principles entries, including the 2020 customisation-tool extension of IKEA Effect. Proper Cloth's quiz, fit-point count, fabric and collar range, and remake terms come from Proper Cloth's Smart Sizes page, its design tool, and its published FAQs. Son of a Tailor's quiz, algorithm claims, design tool, and production process come from its FAQ and About Us pages. The above-95% accuracy line is Son of a Tailor's own claim, not an independent study. Trustpilot figures were whatever the site showed while this page was researched and change continuously; check Trustpilot for current numbers. Features and prices move too; use each company's site for what applies now. “What changes on the second order” reapplies the same five cited mechanisms to a repeat purchase. Neither brand has published returning-customer data for that section, so read it as reasoning from the cited studies rather than a separately sourced finding.

Real examples
  • Proper Cloth Decoded above: Smart Sizes quiz, 16 fit points, free remake when the first cut misses propercloth.com
  • Son of a Tailor Also decoded above: five-question Ideal Size model, one named sewer per garment sonofatailor.com
  • Indochino Made-to-measure suits and shirts via an online measurement quiz, with in-person appointments in some cities indochino.com
  • MTailor Replaces the questionnaire with a 360-degree phone video; computer vision estimates roughly 60 measurements mtailor.com

Operating providers listed to show the same pattern elsewhere. None is an endorsement. Features and pricing shift; use each provider's own site for what applies today.
Why does GoalSaver's 4.75% bonus feel like money you'd be losing, not money you haven't earned yet?

CommBank's GoalSaver currently advertises 5.00% p.a. on balances up to $49,999. That headline is a fixed 0.25% base plus a 4.75% bonus paid only in a calendar month that has at least one deposit and no withdrawals.

Four mechanisms lean on that one bonus rule in sequence: how losing it feels, what friction sits in front of a withdrawal, why the balance gets a name, and how near the named target looks.

Money & Banking What Feels Protected
Loss Aversion

Describe the pieces separately and the product is a reward: deposit once, leave the balance alone, collect 4.75% on top of a thin base. Present it the way GoalSaver markets it, as one 5.00% rate, and a mid-month withdrawal stops reading as a missed bonus. It reads as giving up most of a return that already seemed attached to the balance. That is Loss Aversion, sharpened by Clawback. The same 4.75% bites harder when framed as something to protect than when framed as something still waiting to be earned, because of which side of the ledger the copy puts it on.

Precommitment Devices

Feeling the bonus as already owned is only half the story. The condition also prices the withdrawal that would forfeit it. Opening GoalSaver involves no formal commitment contract, yet the bonus rule does the same job. It sets a concrete cost on a future withdrawal, chosen while the saver is calm, long before the urge to spend arrives. That is Precommitment Devices without paperwork. The account will not block a transfer. It only makes taking money out cost something measurable the moment it happens, so a planning self can constrain a later, more impulsive one.

Mental Accounting

A priced-in habit still needs a reason to continue. Goal Tracker, paired with GoalSaver in CommBank's app, lets a balance carry a named purpose (a car deposit, three months of emergency cash) instead of sitting as an anonymous total. Once the dollars have a label and a job, they stop reading as spare cash waiting to be spent. Mental Accounting is that filing system: money sorted by purpose, so pulling from a labelled “car deposit” feels more consequential than moving the same amount out of an untitled savings pot.

Goal Gradient Effect

A name says what the money is for. Goal Tracker also shows how near the next checkpoint sits, by splitting the target into weekly instalments. An abstract end total becomes a nearby, concrete one. Goal Gradient Effect documents the same pattern on a coffee loyalty card: effort rises as the visible finish line moves closer, even when the underlying goal is unchanged, because felt distance shrank. Across the four stops the bonus condition is constant. It is felt as a loss to avoid, backed by a real cost, filed under a purpose worth keeping, and shown getting closer each week.

Real vs. perceived
Genuinely real
  • GoalSaver's rule is binary: any withdrawal in the calendar month drops the whole balance to the 0.25% base for that month
  • Westpac Life and ING Savings Maximiser use a looser net-growth test by month-end, so a replaced withdrawal can still keep the bonus in a way GoalSaver does not allow
  • Bonus rates are balance-capped (GoalSaver up to $49,999; ING Savings Maximiser up to $100,000), limits each bank discloses in its own terms
Psychological framing
  • Loss Aversion: one combined 5.00% figure makes breaking the rule feel like losing earned interest rather than skipping a future reward
  • Precommitment Devices: a concrete cost attached ahead of time to a future withdrawal, with no signed lock-up
  • Mental Accounting: a named goal balance reads as already allocated rather than as free cash
  • Goal Gradient Effect: weekly milestones make a distant savings target feel near enough to keep funding
Sources

Each mechanism above is cited on its Principles entry, covering Loss Aversion (Tversky & Kahneman, 1991), Precommitment Devices (Ariely & Wertenbroch, 2002), Mental Accounting, and Goal Gradient Effect. GoalSaver's rate, condition, and balance cap come from CommBank's GoalSaver page and CommBank's guidance on earning the bonus. Goal Tracker's milestone behaviour comes from CommBank's Goal Tracker page. Rates and conditions change; check CommBank directly rather than treating this summary as current.

Real examples
  • CommBank GoalSaver Decoded above: 5.00% p.a. up to $49,999, zero withdrawals required each month commbank.com.au
  • Westpac Life Looser rule: grow the balance by month-end; withdrawals are fine if replaced in time westpac.com.au
  • ING Savings Maximiser Also net-growth based, plus a linked transaction deposit and card-use requirement ing.com.au

Operating providers listed to show the same pattern elsewhere. None is an endorsement. Rates and conditions shift; use each provider's own site for what applies today.

How does Up Bank's behavioural design pay off for both the bank and its customers?

Up is an Australian neobank: no branches, no counter service, the whole product lives in the app. That is a different design brief from a bank like CommBank, which still runs both a branch network and an app. Walk the product in the order its features show up and one pattern keeps repeating. It begins with a small saving habit and climbs to the app's largest ask, a home loan. Then it drops to the smallest, a $5 coffee refunded on a live page where a prize pool ticks down and a win ticker updates within minutes. On 1 September 2026 a further stop joined the list under a different rule than the seven before it: protecting money the customer never chose to earmark, the recurring bills underneath everything else.

At each of the eight stops below, Up chose the version of the mechanism that keeps deposits and daily use on the bank's side. It does that while still delivering the customer the benefit the mechanism is meant to provide.

Money & Banking What Feels Effortless
Loss Aversion
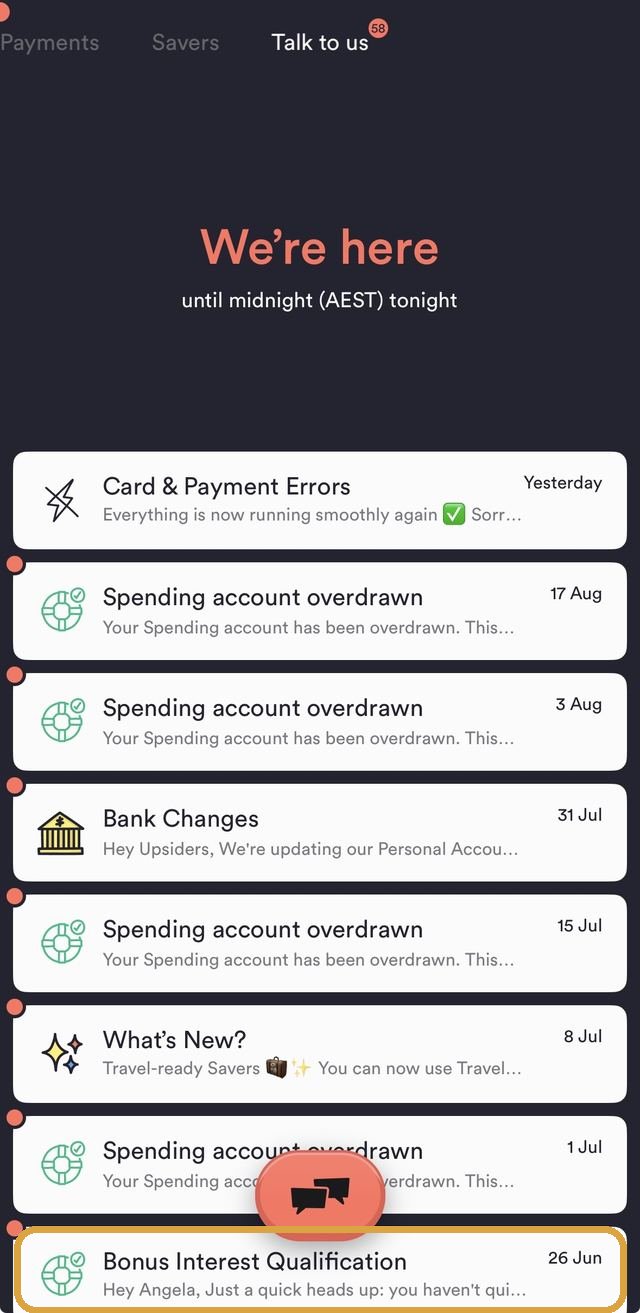
Up's 'Talk to us' inbox, the 'Bonus Interest Qualification' row boxed, warning a customer they haven't yet qualifiedBoxed: the proactive nudge, sent before the bonus lapses

The journey's simplest moment is a bonus already half earned and about to expire. Up's Savers use a monthly activity condition in the same family as GoalSaver. Partway through the month, the “Talk to us” inbox can send a “Bonus Interest Qualification” alert to anyone who has not met it yet. That is a straight use of Loss Aversion and its cousin Clawback. Letting the rate lapse and keeping the spread would be the bank-friendly default the mechanism alone predicts. Up instead spends a notification explaining how to keep the rate it has already framed as the customer's.

Precommitment Devices

A mid-month warning only helps after the risk is live. Locked Savers move the protection earlier with Precommitment Devices and no paperwork. A customer can put a Saver behind a real three-hour delay before the money unlocks again, and can also nominate a mate on Up who can release it sooner if asked. The delay is friction chosen while calm, attached to a future withdrawal before temptation exists. The mate key adds a social layer: asking another person to break the lock costs more than tapping a button alone.

Mental Accounting
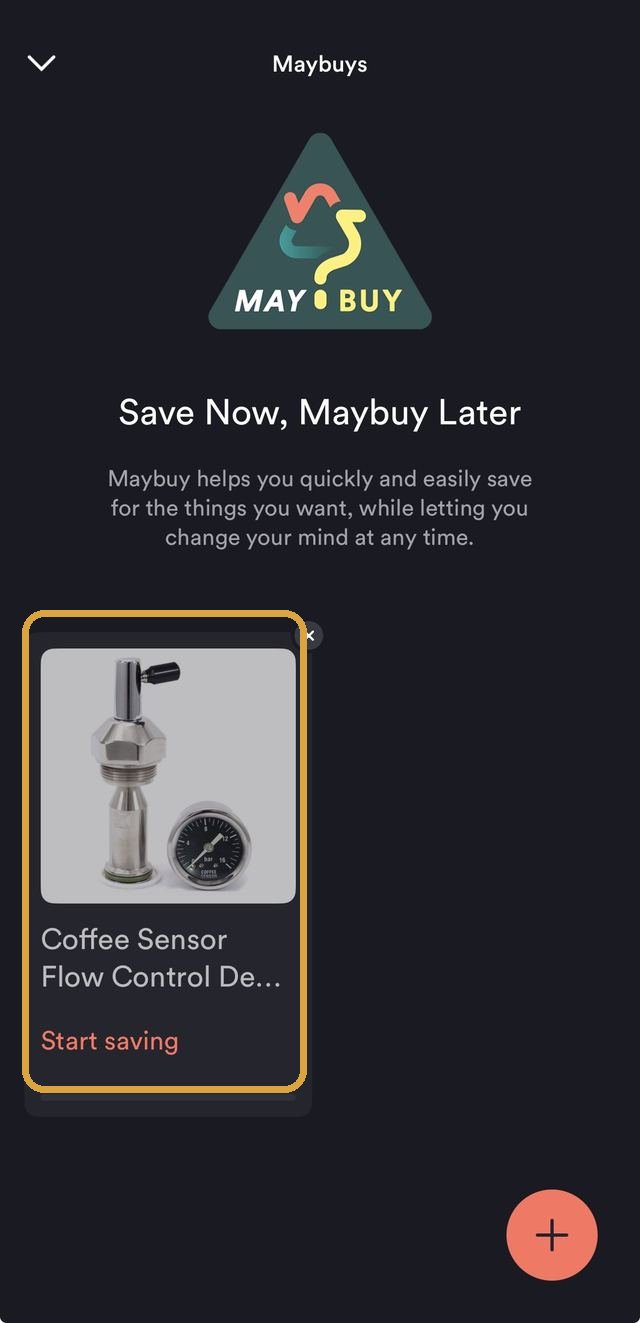
Up's Maybuys feature, the product card boxed: 'Save Now, Maybuy Later', saving towards a real photo of a specific coffee machine partBoxed: a photo of the actual thing, not a number

A lock still needs a reason strong enough to leave alone. Up's next step sharpens Mental Accounting past a label. Savers can take a name and an emoji (up to 50 of them), so a balance reads as “Home Deposit” or “Holiday” instead of a bare figure. Maybuys goes further: it saves toward a photo of the product itself, pulled from a listing, “while letting you change your mind at any time.” Dollars filed against a pictured item are harder to spend casually than the same dollars in an untitled pot.

Goal Gradient Effect
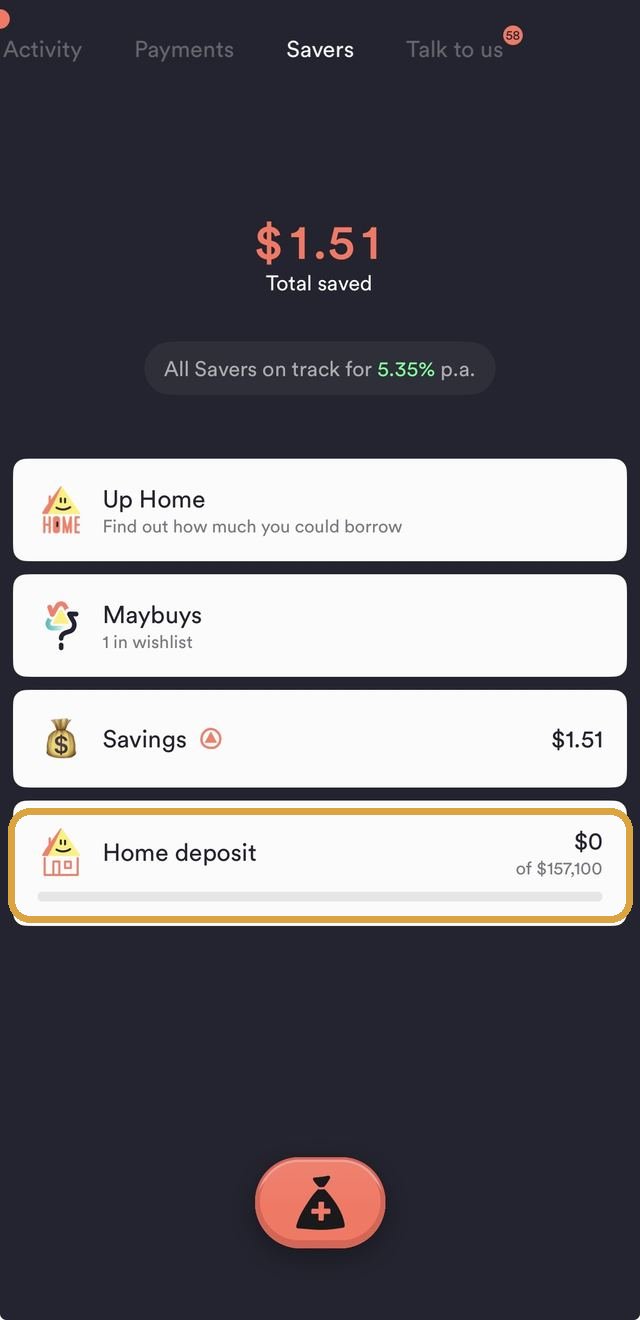
Up's Savers list, the Home deposit row boxed: its own progress bar against a real target, at $0 of $157,100Boxed: the one Saver still at $0 of its target

A named Saver says what the money is for. It does not show remaining distance. That is where Goal Gradient Effect enters. Every Saver draws its own progress bar against its real target in the account list, not buried a tap away. Coffee cards use the same cue: follow-through rises as the finish line looks nearer, even when the goal itself is unchanged. A bar at $0 of $157,100 and a bar at $140,000 of $157,100 describe the same remaining maths with very different felt urgency.

Chunking
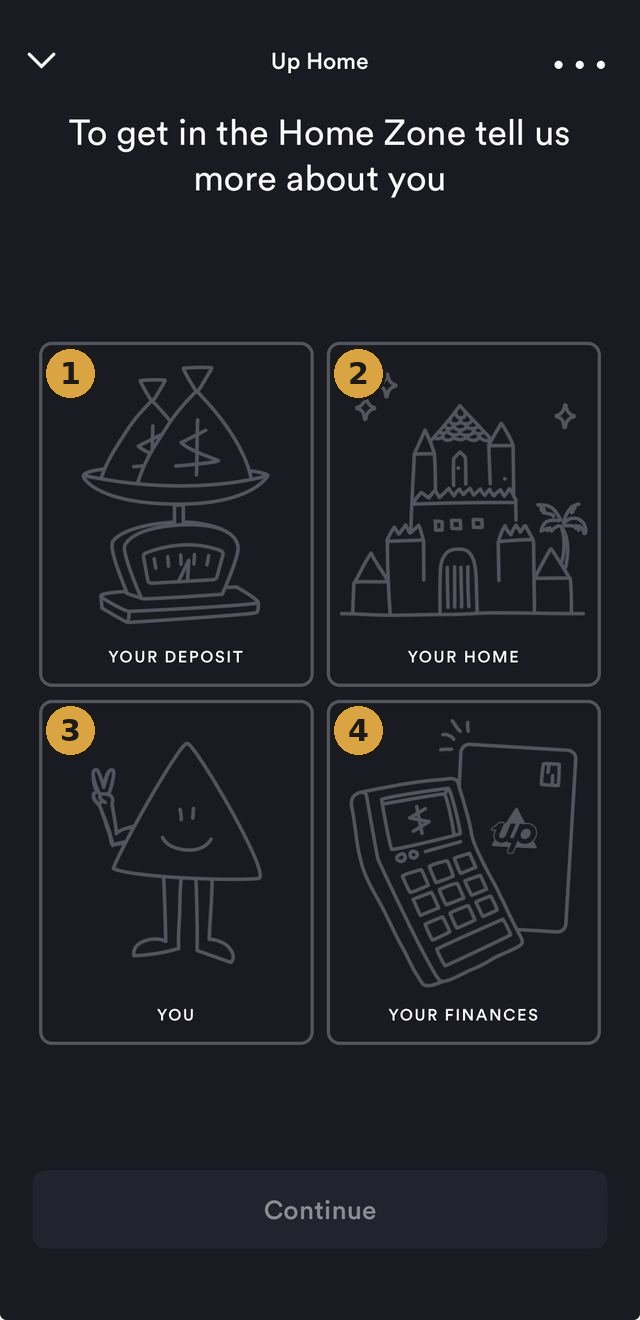
Up Home's borrowing-power intake, numbered 1 to 4: Your Deposit, Your Home, You, Your FinancesNumbered: one long form, split into four labelled steps

The first four stops all sit on everyday saving. Up applies the same instinct, Chunking, to the app's largest ask: a home loan. The Home Zone borrowing-power tool never arrives as one unbroken disclosure form. It is four labelled sections (Your Deposit, Your Home, You, Your Finances). The deposit goal gets the same treatment, turning $157,100 into “$2,618.34 every fortnight” with a projected date. One flow applies the mechanism twice: once to the intake task, once to the number. Several smaller asks clear a mental bar that the full amount at once would miss.

Scarcity
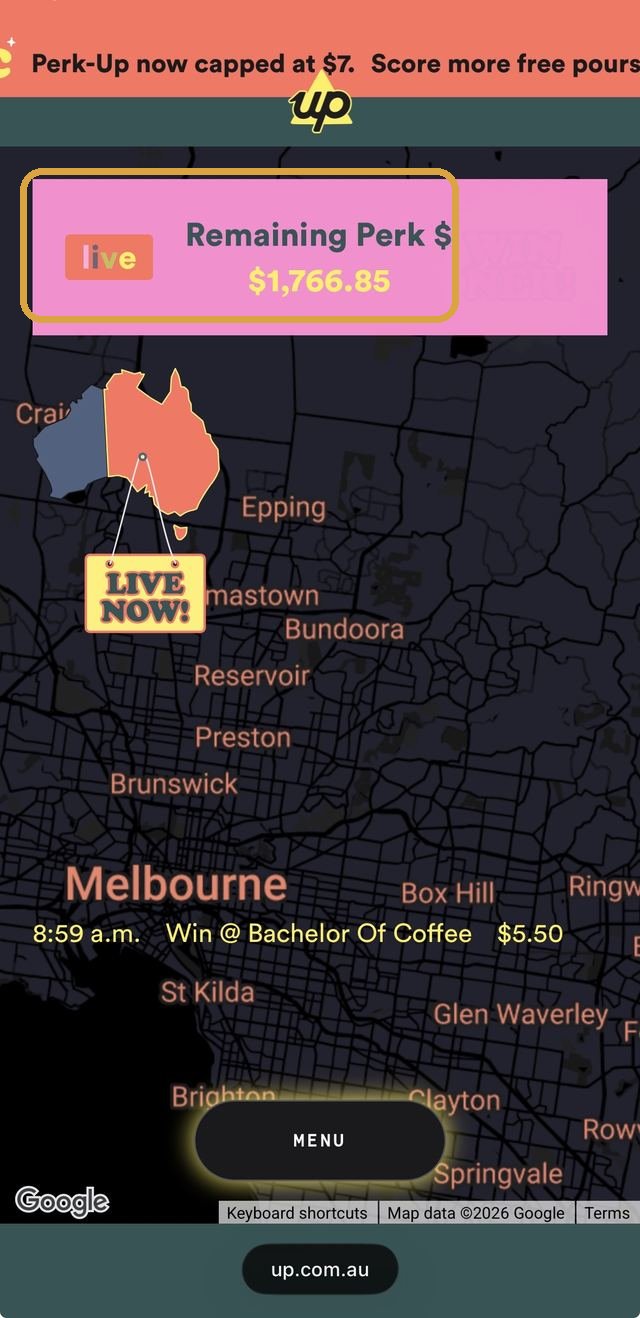
Up's Perk-Up live web page, the 'Remaining Perk $1,766.85' pool boxed, above a real-time map of where wins are happeningBoxed: the pool, ticking down in real time

From a six-figure deposit to a weekday coffee, the design logic reappears, now aimed at $5 rather than a home. This time Scarcity is numeric rather than implied. Perk-Up refunds one small coffee (up to $5) per person on eligible weekday mornings from a promotional pool with a published cap. The live page shows that pool as a single countdown, “Remaining Perk $1,766.85,” falling as wins land. The reward is not merely limited in the fine print; it is visibly draining on screen, a stronger cue than a flat “while supplies last.”

Social Proof
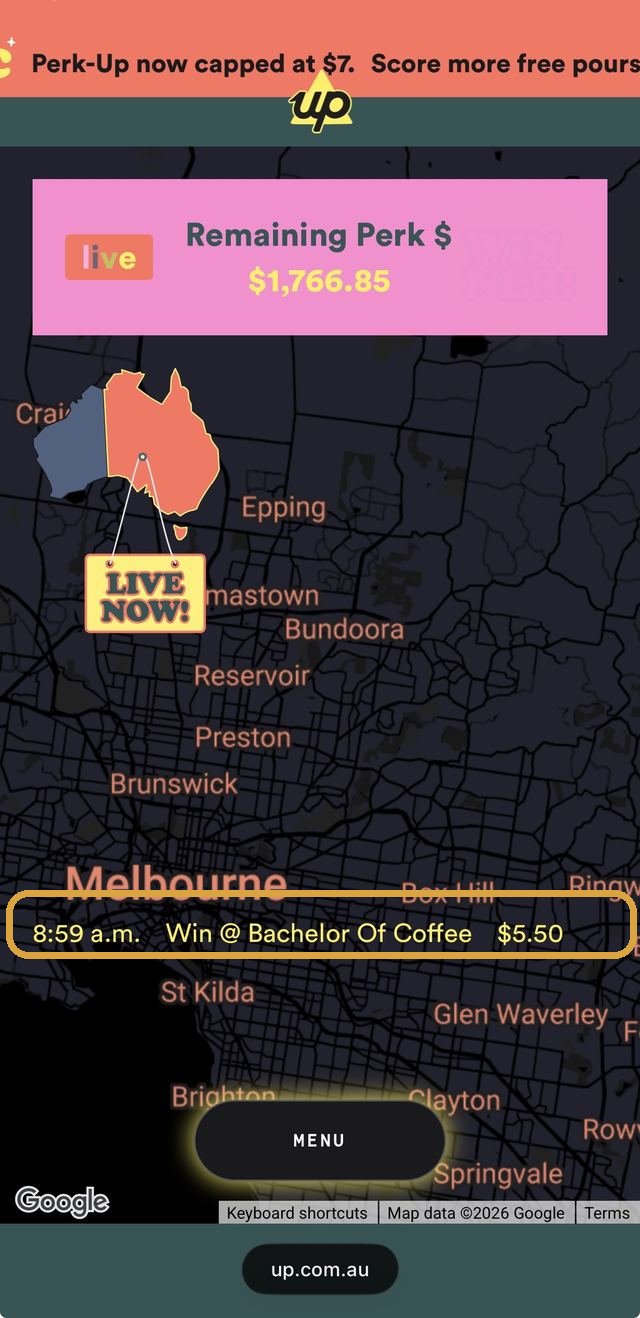
The same Perk-Up live page, the real-time win ticker boxed: '8:59 a.m., Win at Bachelor Of Coffee, $5.50'Boxed: a real win, timestamped, minutes ago

A draining pool would already create urgency. Up pairs it with Social Proof on the same page: a live win ticker such as “8:59am, Win @ Bachelor Of Coffee, $5.50,” refreshing as wins happen and plotted on a map. Seeing nearby people win in the last few minutes makes trying feel more worthwhile than a static banner claiming the same odds.

Pain of Paying
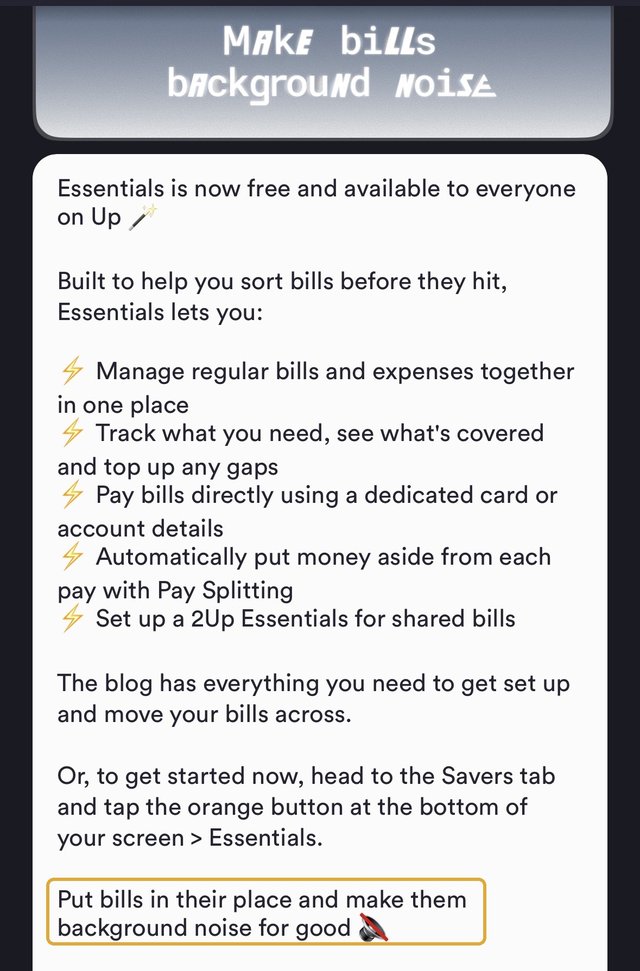
Up's in-app 'What's New' announcement for Essentials, the closing line boxed: 'Put bills in their place and make them background noise for good'Boxed: Up's own name for the mechanism

Every earlier stop protected money the customer chose to set aside: a Saver, a deposit target, a coffee perk. Essentials, launched 1 September 2026, protects money that arrives on its own schedule: bills and subscriptions. It gathers those recurring payments into their own account, estimates how much each pay must cover, moves that amount automatically via Pay Splitting, then pays from a dedicated card when the bill lands. Paying the bill never has to feel like a fresh decision, because the allocation already happened on payday. Pain of Paying runs in reverse here the way a prepaid coffee subscription does: the money leaves earlier than the moment of use, so the later moment hurts less. The same decoupling now covers electricity and streaming as well as coffee. Up's own line for the result is the most literal label on this page: “make bills background noise.”

Across all eight stops the pattern holds: a real mechanism aimed at a real behaviour, and Up's upside only arrives once the customer actually receives what the mechanism promised. A kept bonus rate. A habit that sticks. A funded home loan. A coffee refunded. A bill that never feels like a surprise.

Real vs. perceived
Genuinely real
  • The Home Zone's borrowing estimate and deposit-goal maths use real inputs (property price, income, existing savings), not a fixed marketing figure
  • Locked Savers' delay is a genuine 3 hours, disclosed on Up's own blog, rather than an indefinite or hidden lock
  • Perk-Up's remaining pool and per-person daily cap are published limits under the promotion's actual terms
  • Up Home's advertised rate (5.95% p.a. comparison rate at time of writing) is a single published number, not a teaser that resets after an intro period
  • Essentials has its own BSB and account number plus a dedicated digital debit card: a separate account, not a label inside Spending
Psychological framing
  • Loss Aversion: a proactive warning frames the bonus as already the customer's to lose rather than a reward still to earn
  • Precommitment Devices: a modest three-hour obstacle, plus an optional social cost, stands in for self-control in the moment
  • Mental Accounting: a named Saver or a product photo makes the same dollars feel less spendable than an unlabelled balance
  • Goal Gradient Effect: a visible progress bar changes how near a goal feels without changing the goal
  • Chunking: $157,100 clears a different mental bar as four labelled steps and a fortnightly figure than as one lump sum
  • Scarcity and Social Proof: a countdown pool and a live win ticker make fixed odds feel more urgent and more winnable than the same odds stated plainly
  • Pain of Paying: funding bills ahead of time does not change their cost; it changes whether paying them feels like a decision
Where it could go further
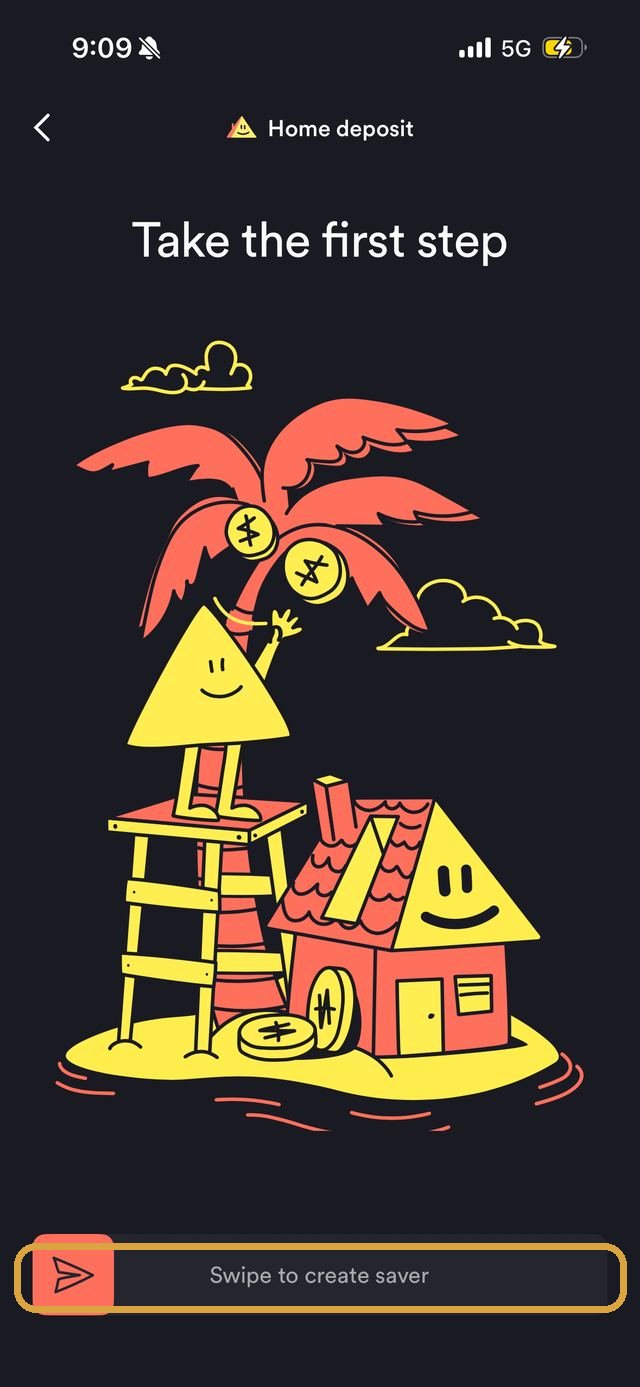
Up Home's final confirmation screen for a deposit Saver, the 'Swipe to create saver' gesture boxedBoxed: the one moment Up adds friction on purpose

The same “Talk to us” inbox that warns before bonus interest lapses still handles overdrafts after the fact. Several “Spending account overdrawn” alerts can land on one account across months, each sent only after the overdraft already exists. Up has already shown, with the bonus nudge, that it can warn before a real cost hits. A low-balance alert before an overdraft, rather than only a notice after, would reuse a pattern Up has already validated. Essentials, launched the same day as this write-up, aims at that gap for bills by setting money aside before a bill lands. Whether it cuts these particular overdraft alerts in practice is still unknown; that needs usage data Up has not published.

Locked Savers use one fixed three-hour delay for every Saver, whatever the size or purpose. That is not a flaw to loosen lightly. This site's Precommitment Devices citation (Ariely & Wertenbroch, 2002) found that externally set constraints reliably beat ones people set for themselves. Letting customers pick the delay would risk undercutting the mechanism. A tighter extension would keep the delay bank-set but tier it by stake. Keep three hours for everyday Savers. Use a longer default (a day, for example) for a large, slow goal such as a Home Deposit Saver. A coffee-sized wait is a much smaller relative barrier on a six-figure balance than on a small one.

Sources

Each mechanism above is cited on its Principles entry: Loss Aversion (Tversky & Kahneman, 1991), Precommitment Devices (Ariely & Wertenbroch, 2002), Mental Accounting, Goal Gradient Effect, Chunking, Scarcity, Social Proof, and Pain of Paying. Up feature detail comes from Savers, Locked Savers, Hi-Fi, and Perk-Up (plus its terms), as well as Essentials and The Tree of Up roadmap. Rates, conditions, and screens move; check Up's site and app rather than treating this summary as current.

Real examples
  • Monzo, Pots & Roundups UK neobank: named savings pots plus automatic spare-change roundups into them monzo.com
  • Revolut, Vaults UK/EU neobank: named goal-based savings vaults with automatic roundups revolut.com

Operating providers listed to show the same category of feature elsewhere. None is an endorsement. Features and terms shift; use each provider's own site for what applies today.

Why does a $2.50 fries deal come with a chance to win free food for life?

On the McDonald's Australia app in 2026, Today's Golden Deal offered large fries for $2.50, pickup only, gone at midnight. Directly under the price sits the line that carries the pitch: “Plus, a chance to WIN!”, which enters the buyer into a draw for free McDonald's food for life. Nothing on this screen states the odds. Those live behind a separate “View terms of this offer” link a customer has to leave the deal to open.

Food & Drink What Feels Lucky
Probability Weighting

Left alone, $2.50 fries is an ordinary discount: easy to stack against yesterday's price and discard by lunch. Attach a prize draw and the purchase stops reading as a routine bargain. Once the same order carries “a chance to win” something as concrete as free food for life, people stop pricing the (likely tiny) odds with any precision. Tiny chances get treated as roughly interchangeable and worth chasing, the same tilt that makes a lottery ticket feel sensible. The golden coin badge and “Today's Golden Deal” banner charge the moment. The real win probability sits one tap away in the terms, where most $2.50-fries buyers never look.

The tilt has a measurable emotional side. A 2020 field experiment found that simply holding a lottery-style ticket raises happiness in the hours before the draw, win or lose. Separate work shows people overweight a small chance of something affect-rich more than an equally small chance of plain cash. The fries purchase also buys a few minutes of felt hope, an emotional lift that does not track the true odds of collecting.

Probability Weighting is the name for that gap: how large a tiny chance feels, and how exciting it is, tracks the framing more than the number.

Framing Effect

McDonald's own McGold Card competition terms set the prize at $30 a week for 40 years, about $62,400 in total. Eight McGold Card winners and 40 Silver Card winners share a stated $561,600 pool. The prize is real and generous, and it is capped: a fixed weekly allowance across four decades, not the open-ended picture “for life” suggests. The underlying benefit stays the same under either wording. Only which wording appears on the deal screen changes.

Framing Effect is why that choice matters. The same $62,400 capped benefit, labelled “free food for life,” reads as an open-ended windfall; labelled “$30 a week for 40 years,” it reads as a fixed allowance. Affect-rich wording also matches what Rottenstreich and Hsee found gets overweighted relative to a plain figure of equal value, which loops back into the Probability Weighting tilt above.

Spotted in the wild

Framing copy and the prize count above, taken from McDonald's Australia's own promo pages.

McDonald's Australia's September Golden Deals page reading “each deal is your chance to win free Macca's for life”

McDonald's Australia's own September Golden Deals page: “each deal is your chance to win free Macca's for life,” captured September 2026.

McDonald's Australia's McGold Card page reading “With just eight up for grabs across Australia”

The McGold Card's own page on mcdonalds.com.au: “with just eight up for grabs across Australia,” confirming the eight-winner figure decoded above directly from McDonald's own terms, with the real Silver Card, the second prize tier, shown below it, captured September 2026.

This is McDonald's own marketing language, not proof the prize draw sold more fries or made customers feel better about the deal. The vivid “free Macca's for life” wording, and the real McGold Card winner count, are exactly as McDonald's states them on these pages.

Real vs. perceived
Genuinely real
  • A $2.50 large fries deal, valid the one day it's shown, redeemable either through an in-app pickup order or a MyMacca's Rewards code at drive-thru, kiosk, or counter
  • The prize draw's actual odds, entry mechanics, and eligibility sit behind a separate “View terms of this offer” link, not on the deal screen itself
  • The $2.50 fries purchase is what enters a customer into the draw; nothing about the fries themselves changes
  • The McGold Card prize itself, per McDonald's own competition terms: up to $30 a week for 40 years, about $62,400, split across 8 McGold Card and 40 Silver Card winners from a stated $561,600 total pool
Psychological framing
  • Probability Weighting: attaching a prize draw makes an ordinary, near-certain $2.50 purchase feel newly charged
  • Probability Weighting: unstated odds still sell the offer, because almost any small chance framed as a win feels worth chasing
  • Probability Weighting: the bundled deal feels more valuable than a bare $2.50 fries discount on its own
  • Probability Weighting: hope during the buy decision is a measured emotional lift, whether or not the draw pays out
  • Framing Effect: the same $62,400 cap reads as an open-ended windfall as “free food for life” and as a fixed allowance as “$30 a week for 40 years”
Sources

Probability Weighting and Framing Effect each carry their academic citations on the Principles page: Kahneman & Tversky (1979) and Levin & Gaeth (1988). Two further papers sit behind the emotional claims above: Rottenstreich & Hsee (2001) on affect-rich probability weighting, and Burger, Hendriks, Pleeging & van Ours (2020) on the measured happiness lift from holding a ticket. Price, terms layout, and redemption options come from the McDonald's Australia app screen itself, captured 2026. Deals like this rotate daily, so check the app for what is live. McGold Card structure ($30 a week for 40 years, 8 McGold and 40 Silver winners, $561,600 pool) is reported from McDonald's Australia's September 2026 McGold Card competition page, with independent coverage matching the same outline. Screenshots above confirm the eight-winner figure, the “free Macca's for life” wording, and the Silver Card tier against McDonald's own site. The $30-a-week / 40-year figure, Silver Card winner count, and total-pool number still rest on that secondhand coverage rather than a personally re-checked primary terms PDF.

Real examples
  • McDonald's Monopoly McDonald's own long-running annual promotion, distributing instant-win and collect-to-win game pieces to purchases made through the MyMacca's App mcdonalds.com
  • Hungry Jack's Sip & Score A 1-in-3 chance to win instant prizes with any coffee or iced drink bought through the Hungry Jack's App or loyalty card frugalfeeds.com.au
  • Bankwest Easy Saver A chance for 50 monthly winners to get an 11.50% p.a. “Interesting Rate” for opening a savings account with a code, versus a guaranteed 5.75% p.a. intro rate for everyone else, framed as: “Not a winner? You'll still feel like one” bankwest.com.au

Operating promotions listed to show the same mechanism elsewhere. None is an endorsement. Terms and odds shift; use each brand's own site for what applies today.

Why does Bankwest say you're “still a winner” even when you lose the draw?

Bankwest's 2026 “Interesting Rates” campaign enters anyone who opens an Easy Saver with a promo code into a draw for an “Interesting Rate” of 11.50% p.a. fixed for four months on top of a savings account many people would open either way. Fifty winners each month land that headline rate. Everyone else is told they are “still a winner” for opening the same account they would have opened without winning. The first monthly round's code was literally DENIM: a playful theme that does not change the odds.

Walk the flow in the order an applicant meets it and three mechanisms each take a turn. The 11.50% headline pulls a second look at opening the account. The rate paid to everyone else is relabelled so missing the draw barely registers as a loss. The extra entry step, downloading an app, is cast as something forfeited by skipping rather than a mild inconvenience.

Money & Banking What Feels Lucky
Probability Weighting

Without the draw, Easy Saver's everyday offer is a competitive but ordinary 5.75% p.a. introductory rate, later 5.00% p.a. ongoing, both capped at balances up to $250,000.99. That alone is one more savings product to stack against ING or Westpac. Pairing it with a monthly draw for a much higher rate changes the decision. Nowhere in the promotion states the odds of landing among 50 winners a month, or how many coded openings happen that month. Under Probability Weighting, the 11.50% figure gets treated as a live, reachable outcome rather than a number hanging off odds neither the bank nor the applicant can compute from the materials shown.

Framing Effect

A headline prize this sharp also needs a soft landing for everyone who misses it, and Bankwest put that landing on the screen itself. The ordinary introductory rate, 5.75% p.a., the rate every non-winner receives either way, sits under a black “Still a ‘winner’” badge. Confirmation copy adds: “Not a winner? You'll still feel like one with a 5.75% p.a. variable intro rate.” The rate number is unchanged. Only the badge and wording above it change. That is Framing Effect: call the same base rate a consolation and it reads like second place; call it a win and it reads like one.

Loss Aversion

Relabelling the fallback rate softens missing the draw. The next screen targets a different sticking point: installing an app only to open a savings account. Continue in a browser and Bankwest still allows it, but puts a cost on that path: “Skip the app? You'll miss your chance to enter,” placed directly above the button that continues online anyway.

An app install is usually a neutral extra step, easy to postpone. Under this wording, the download sits between the applicant and a prize already wanted. That is Loss Aversion: the same optional install reads differently once skipping it is described as giving something up.

Spotted in the wild

Screens from Bankwest's own “Interesting Rates” flow, one per mechanism above, captured 2026.

Bankwest promotion screen reading 'Chance to win our interesting Rate, fixed for 4 months, 11.50% p.a., Up to $250,000.99' with no odds of winning stated anywhere on the card

Bankwest's own competition screen: “Chance to win our interesting Rate, fixed for 4 months” at 11.50% p.a., with no odds of winning shown anywhere on the card.

Bankwest screen showing a black 'Still a winner' badge over the ordinary 5.75% p.a. rate that every non-winning applicant receives

The exact rate every non-winner gets anyway, badged “Still a ‘winner’” rather than presented as the plain fallback rate it is.

Bankwest app-download screen reading 'Skip the app? You'll miss your chance to enter.' above a Continue online button

The screen shown when an applicant tries to continue in a browser: “Skip the app? You'll miss your chance to enter.”

Real screens from a currently operating Bankwest promotion, shown to illustrate the mechanisms decoded above at work, not to claim the campaign is deceptive or that any of these figures are inaccurate. Screens, rates, and copy move with each monthly round, check Bankwest's own site for what's live today.

Real vs. perceived
Genuinely real
  • Published rates: 11.50% p.a. fixed for 4 months (50 monthly winners only), 5.75% p.a. variable intro rate (everyone else, first 4 months), 5.00% p.a. ongoing standard variable rate, all up to $250,000.99
  • The competition runs across three monthly rounds with their own entry codes, open to WA, NSW, VIC and QLD residents 18+, maximum one entry and one prize per person
  • The Bankwest app can genuinely be skipped; a working “Continue online” option sits on the same screen as the warning against it
Psychological framing
  • Probability Weighting: 11.50% is weighted as reachable even though the odds stay unstated and uncalculable from the materials shown
  • Framing Effect: the 5.75% every non-winner already receives is labelled a “win” rather than a consolation
  • Loss Aversion: skipping the app reads as forfeiting an entry already in hand, rather than declining an optional convenience
Sources

Probability Weighting, Framing Effect, and Loss Aversion each carry their academic citations on the Principles page (linked throughout): Kahneman & Tversky (1979), Levin & Gaeth (1988), and Tversky & Kahneman (1991). Rates, codes, and screen copy come from Bankwest's “Interesting Rates” promotion and published competition terms, captured 2026. Rounds and rates change, so check Bankwest's site and terms rather than treating this summary as current.

Real examples
  • Bankwest Interesting Rates The promotion decoded above: 11.50% p.a. fixed for 4 months for 50 monthly winners, everyone else gets 5.75% p.a. bankwest.com.au
  • McDonald's Australia app The same overweighted-chance mechanism decoded on a $2.50 fries deal with a draw for free food for life Decoded above

Operating promotions listed to show the same mechanisms elsewhere. None is an endorsement. Rates, codes, and terms shift; use each provider's own site for what applies today.

Why does a Netflix session keep going long after the show you actually chose has ended?

A Netflix visit is one continuous session, not a single static screen. Five live features appear in the order a subscriber actually hits them. Personalised artwork on the opening row. A numbered Top 10 a few scrolls down. A Leaving Soon tag on titles about to expire. An episode that starts itself. And the narrative reason few people cancel that countdown.

None of the five is secret. Each is a small, well-documented design choice on its own. Stacked together they speak to what Netflix's own engagement metrics keep measuring: how far into a session a subscriber goes before actively choosing to stop, if they stop at all.

Tech & Product Design What Feels Endless
Salience

Home rows open on personalised artwork rather than one fixed poster. Netflix engineering has published that the platform keeps more than 100 candidate images per title. An algorithm picks the image an account is most likely to click, weighted by genres, actors, and moods that account already watches. A thriller fan and a rom-com fan can see two different images for the same film. Salience is the mechanism: whichever attribute already stands out for that viewer, a familiar face or tone, gets visually foregrounded. In the split-second click decision, the option carrying that cue is weighted far more heavily than any change in the title's actual content.

Social Proof

Personalised art only gets a title into view. A few rows down, the numbered Top 10 supplies a faster reason to stop scrolling: Social Proof made literal. Each title in that row carries a visible rank from 1 to 10, recalculated daily within each country, showing how many other accounts have already been choosing it. The rank never claims a given subscriber will enjoy the title. It only reports what everyone else has already been watching in aggregate.

Scarcity

Top 10 borrows other people's behaviour. A “Leaving Soon” tag borrows time, and it predates the ranked list: Netflix has flagged departing titles roughly a month ahead of real licensing expiry for years. That cue runs on Scarcity. Marking how little time remains on the catalogue raises desire in the moment, even for a title a subscriber scrolled past for months without pausing.

Default Effect

Those three cues only get someone to press play once. After the credits, a separate decision takes over. The next episode starts on its own behind a short on-screen countdown the subscriber must cancel to stop. That is Default Effect in plain form. The path that needs no action is chosen far more often than the same next episode would be if every play required reaching for the remote. Inertia becomes continuation.

Curiosity Gap

Those four features still leave one question open: why let the countdown run instead of cancelling it. The answer sits in the episode that just finished more than in the chrome of the app. A strong ending leaves at least one thread unresolved: a felt Curiosity Gap, a specific unanswered question the viewer already has enough context to size. That gap turns a ten-second countdown from a barrier into an invitation.

Read the five features as one chain and the throughline is clear: each strips a little friction between a subscriber and the next fifteen minutes. Personalised art eases finding something. A rank eases deciding whether to try it. Leaving Soon eases delaying. Autoplay eases choosing again. The open ending removes the last piece: the sense that stopping here would cost something.

Real vs. perceived
Genuinely real
  • Artwork personalisation runs on a real, published algorithm that picks a genuinely different image per account from a real pool of candidates for each title
  • The Top 10 rank updates from real, live counts recalculated daily within each country, an actual popularity measure rather than fixed marketing copy
  • A “Leaving Soon” tag reflects a real, contractual licensing expiry date, not a manufactured deadline invented to create urgency
  • Autoplay's countdown is a real, short, cancellable window, a few seconds, not an unstoppable auto-continuation with no way to opt out
Psychological framing
  • Salience: the chosen image is selected for what will catch this viewer's eye; whether it matches the title's content or quality is a separate question
  • Social Proof: a high rank reflects aggregate popularity elsewhere, separate from whether the title fits this viewer's taste tonight
  • Scarcity: Leaving Soon urgency tracks a licensing window, not whether the title suits tonight's mood
  • Default Effect and Curiosity Gap: keeping watching by default reflects inertia plus an open narrative question more than a deliberate keep-going decision
Sources

Each mechanism above is cited on its Principles entry (linked throughout): Salience, Social Proof, Scarcity, Default Effect, and Curiosity Gap. Artwork personalisation comes from Netflix engineering's published account of the system. Top 10 and “Leaving Soon” are long-documented, currently live app features; check Netflix for what is showing today, since ranks and expiry dates move daily. The separate “Match” percentage badge is left out on purpose. Multiple outlets reported in 2026 that Netflix was phasing it out for descriptive tags, and a block built around a feature already vanishing for some subscribers would misstate what the app shows now.

Also worth reading: The Channel Netflix Spent a Decade Killing Might Be Coming Back, this site's special report on Netflix's reported plans for always-on channels. Those channels target a separate choice-overload problem before a subscriber ever reaches the features decoded above.

Real examples
  • Spotify, personalised cover art Discover Weekly and other algorithmic playlists generate their own per-account cover art, the same salience logic applied to music instead of film spotify.com
  • Amazon, Best Seller ranking badges A numbered or badged sales rank shown directly on a product listing, the same literal social-proof cue applied to retail instead of streaming amazon.com

Operating products listed to show the same mechanisms elsewhere. None is an endorsement. Features and rankings shift; use each provider's own site or app for what applies today.